US Tax Services for
Americans Living in Andorra
Living in Andorra does not automatically end your U.S. tax filing and reporting obligations.
US CAN Tax Group helps Americans living in Andorra navigate U.S. federal tax returns, foreign account reporting, international information returns and complex cross-border tax matters. Aleksandr Isakov, CPA (Montana), Principal of US CAN Tax Group, is based in Andorra and available to meet clients in person when needed.
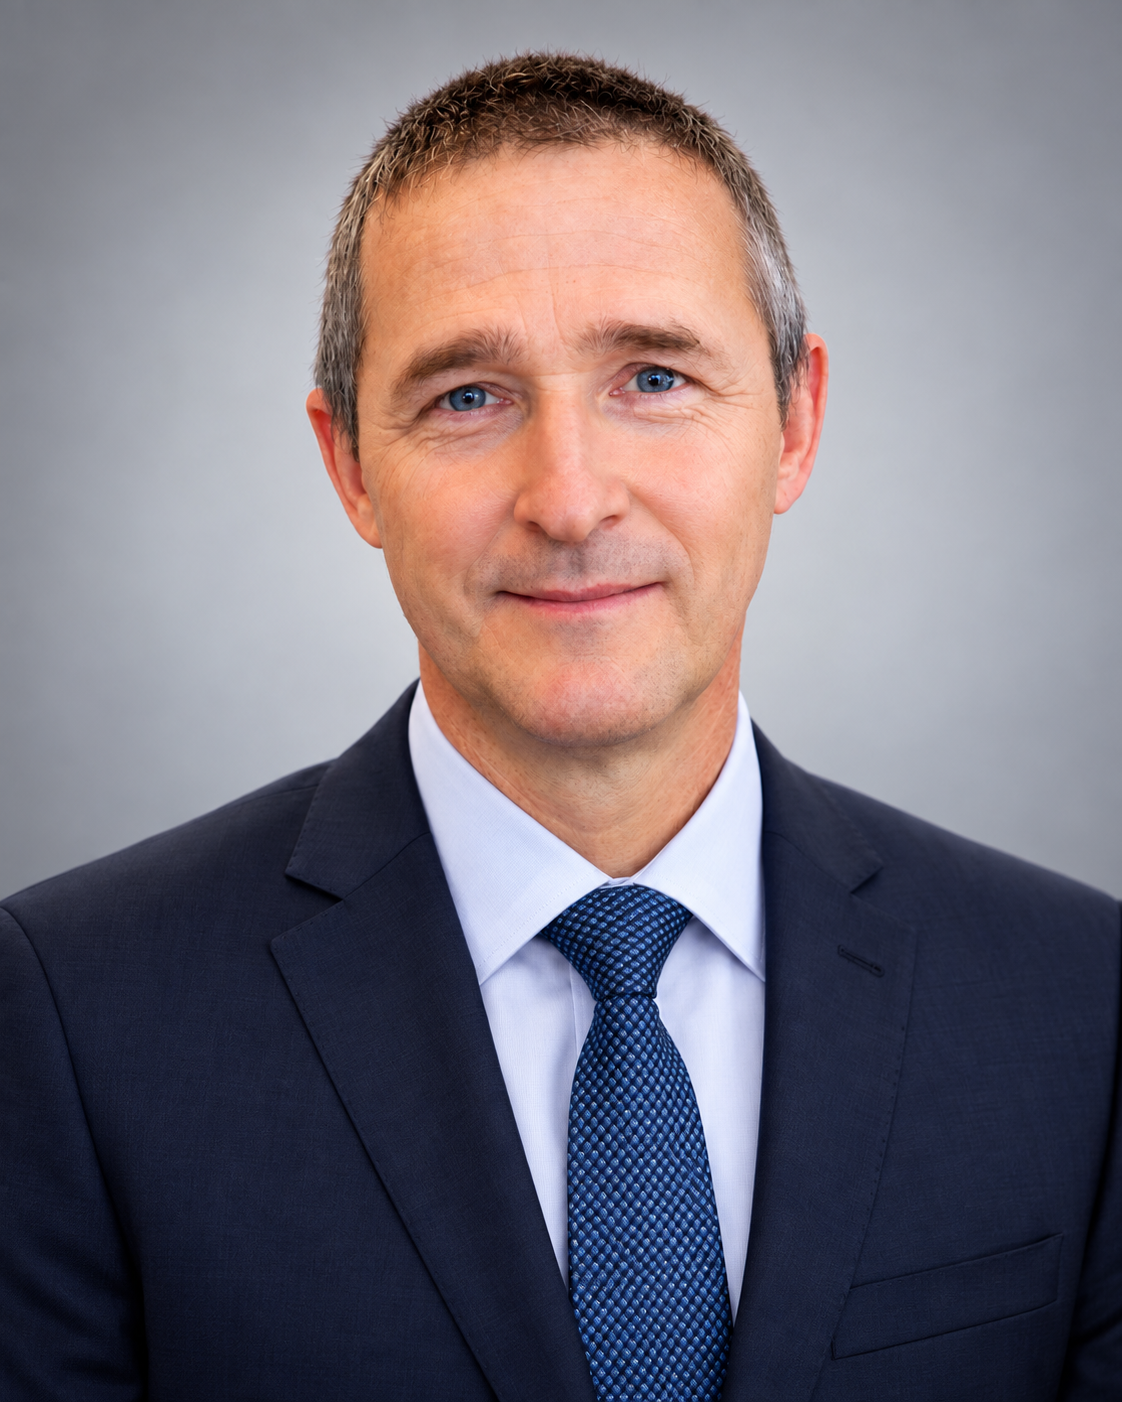
U.S. Tax Expertise, Based in Andorra
Aleksandr Isakov, Principal of US CAN Tax Group, has more than 25 years of experience in U.S. tax and cross-border tax matters. He is a CPA licensed in Montana and a Chartered Professional Accountant in British Columbia, with a Bachelor of Science in Accounting from Carroll College and a Master's in Taxation from Golden Gate University. Before founding his own firm, he worked in the tax department of a Big Four accounting firm.
Do Americans Living in Andorra Still Have to File U.S. Taxes?
In most cases, yes. U.S. citizens and qualifying U.S. resident aliens living abroad are generally subject to U.S. tax and reporting rules on their worldwide income, so living in Andorra does not by itself eliminate U.S. federal filing obligations.
Depending on your circumstances, this can mean an annual U.S. tax return (Form 1040) as well as international information returns covering foreign bank accounts, investments and business interests. Many Americans in Andorra may also have reporting obligations such as the FBAR or Form 8938, and some may be eligible for relief provisions such as the foreign earned income exclusion or foreign tax credits.
Individual filing requirements depend on facts including income, filing status, assets, accounts and other circumstances. Submitting an inquiry is the best way to determine whether we can assist with your situation — see also our guide for U.S. citizens living abroad and our article on whether U.S. citizens abroad have to file U.S. taxes. For a full Andorra-focused walkthrough of Form 1040, FBAR, Form 8938, FATCA and missed filings, read the full guide.
Start Your InquiryU.S. Tax Services for Residents of Andorra
Not every client needs every form — each engagement begins with a review of which U.S. filings and reports actually apply to your circumstances.
U.S. Federal Individual Tax Returns (Form 1040)
Preparation of U.S. federal individual income tax returns for Americans living in Andorra, including all applicable schedules and international forms depending on your circumstances.
State Tax Filing and Planning
Review of state filing and planning questions that can continue to apply to U.S. citizens who move abroad, depending on your prior state of residence and circumstances.
FBAR / FinCEN Form 114
Assessment and preparation of FBAR filings where foreign financial accounts — including Andorran bank and investment accounts — may be reportable.
FATCA / Form 8938
Analysis of whether Form 8938 (Statement of Specified Foreign Financial Assets) applies to you and preparation where required, depending on your assets and thresholds.
Streamlined Filing Compliance Procedures
Guidance and preparation for eligible taxpayers who need to catch up on prior-year U.S. returns and international information filings, where the procedures apply.
Read the full Streamlined Filing guide →PFIC Reporting
Identification and reporting of passive foreign investment companies, which can include European investment funds held from Andorra, depending on your holdings.
Read the full PFIC guide →Foreign Corporation / Form 5471 Reporting
Assessment and preparation of Form 5471 where you own or control an interest in a foreign corporation, depending on your ownership and category requirements.
Read the full Form 5471 guide →U.S. Tax Planning for Americans Abroad
Planning for income, investments, retirement accounts and life changes while living in Andorra, focused on U.S. federal and state tax consequences.
Read the U.S. tax planning guide →Foreign Pension and Retirement Account Review
Review of U.S. tax and reporting questions involving foreign pensions and retirement products, including FBAR, Form 8938, PFIC and foreign trust reporting considerations.
Read the foreign pension and retirement account guide →Foreign Gifts, Inheritances and Form 3520 Reporting
Review of U.S. reporting questions involving foreign gifts, inheritances, family transfers and trusts, including Form 3520 and Form 3520-A where applicable.
Read the foreign gifts and inheritance guide →Prior-Year Compliance and Filing Review
Review of previous U.S. filings and reporting to identify gaps, correct past positions where applicable, and bring prior-year obligations up to date.
Read the prior-year compliance guide →IRS Correspondence / Audit Defense (where applicable)
Support in responding to IRS notices and examinations relating to U.S. filings and international information returns, where applicable to your case.
Do Americans in Andorra Need to File an FBAR?
An FBAR (FinCEN Form 114) may be required if a U.S. person has a financial interest in, or signature authority over, reportable foreign financial accounts whose aggregate value exceeds US $10,000 at any time during the calendar year.
Andorran bank and investment accounts can be foreign financial accounts for U.S. reporting purposes, so account balances are assessed together — not account by account — when determining whether the threshold is met. Whether an FBAR is actually required depends on your individual circumstances, including the type of accounts you hold and your role in relation to them. For background, see our guide to the FBAR for Americans living abroad. For a dedicated Andorra-focused walkthrough, read the full FBAR guide.
Not sure whether your Andorran accounts need to be reported? Submit an inquiry and we'll determine whether we can assist with your reporting questions.
Is There a U.S.–Andorra Income Tax Treaty?
No. Andorra is currently listed by the IRS as a non-treaty country for U.S. income tax treaty purposes.
That does not automatically mean every American living in Andorra will pay tax twice on the same income. U.S. tax treatment may involve provisions such as the foreign tax credit, foreign earned income rules and other provisions depending on the taxpayer's circumstances. The outcome in any specific case depends on the type of income, where it arises and the taxpayer's overall situation.
Because there is no U.S.–Andorra treaty framework to rely on, cross-border planning for Americans in Andorra is generally built around these domestic U.S. provisions. What applies to you is fact-dependent and should be reviewed on your individual facts. See our overview of how U.S. tax treaties work for general background on treaty mechanics.
Does FATCA Apply to Americans With Andorran Bank Accounts?
There is currently no FATCA Intergovernmental Agreement (IGA) between the United States and Andorra. However, Andorran banks are nevertheless subject to FATCA-related obligations, and U.S. taxpayers can still have their own separate U.S. reporting obligations.
It is important to distinguish two different things: the FATCA obligations of financial institutions and the Form 8938 obligations of U.S. taxpayers. These are related but not the same. A bank's compliance with FATCA does not replace or eliminate an individual's own U.S. reporting — Form 8938 may apply depending on your foreign financial assets and the applicable thresholds. For details, see our article on Form 8938 and foreign asset reporting. For a dedicated Andorra-focused walkthrough, read the full Form 8938 and FATCA guide.
In practice, this means your Andorran accounts can be visible to the U.S. compliance system while your own reporting obligations are assessed separately. What applies in your case depends on your accounts, assets and circumstances.
When Should an American Living in Andorra Consider Professional U.S. Tax Help?
Why Americans in Andorra Choose US CAN Tax Group
How the Process Works
Confidential Inquiry
Submit your inquiry and we'll review it to determine whether we can assist.
Secure Document Collection
If we move forward, documents are exchanged through the firm's secure document process.
Review, Preparation and Next Steps
The team reviews the applicable U.S. filing and reporting requirements and guides the client through the agreed engagement.
Frequently Asked Questions
Official Resources
- IRS — U.S. Citizens and Resident Aliens Abroad
- IRS — Filing Requirements for U.S. Citizens and Residents Abroad
- IRS — Form 8938, Statement of Specified Foreign Financial Assets
- IRS — United States Income Tax Treaties (A to Z)
- FinCEN — Report Foreign Bank and Financial Accounts (FBAR)
- Andorran Banking — FATCA
Need Help With Your U.S. Taxes While Living in Andorra?
Submit an inquiry and we'll review whether we can assist with your U.S. filing and international reporting questions.
Start Your InquiryConfidential inquiry process. No obligation.
The information on this page is general educational information and does not constitute individualized tax, legal, immigration or financial advice. U.S. filing and reporting requirements depend on each person's circumstances and applicable law. US CAN Tax Group provides U.S. tax and cross-border U.S. tax services only and does not provide Andorran tax, immigration, residency or local legal advice. For deeper background, browse our cross-border tax guides.
We use optional analytics cookies to understand how visitors use our website and improve its performance. You can accept or reject analytics cookies.