US–Canada Cross-Border
Business Tax Advisory
Cross-border business tax between the US and Canada can create reporting, structural, and compliance issues in both countries. Submit an inquiry and we'll determine whether we can assist before avoidable cross-border problems become more complicated.
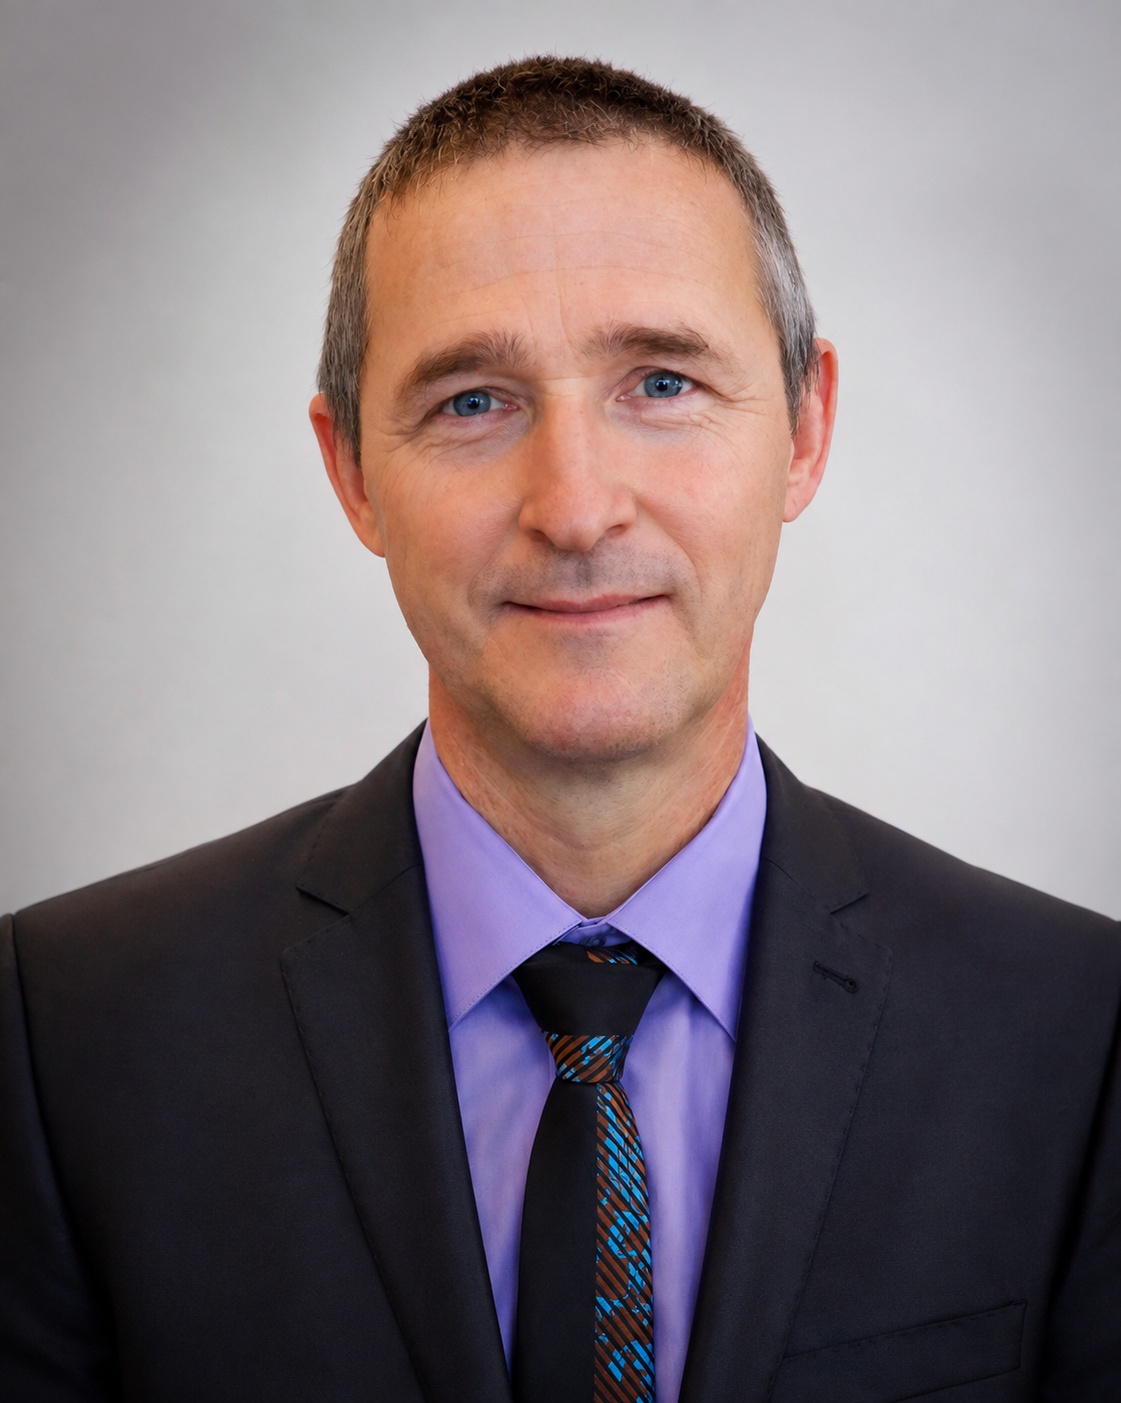
Aleksandr Isakov, CPA
US CAN Tax Group is led by Aleksandr Isakov, CPA, who brings more than 25 years of experience in U.S. tax, cross-border business, and international tax matters.
You May Need Cross-Border Tax Help If…
Start Your Inquiry
Share a few details about your business and we'll review your inquiry to determine whether we can assist and contact you about next steps.
Tax Challenges for Cross-Border Businesses
Operating a business across the US-Canada border introduces a layer of tax complexity that most domestic advisors are not equipped to handle. cross-border business tax challenges are unique: you are subject to two separate tax systems with different rules, rates, and compliance calendars — and mistakes in one jurisdiction can create cascading issues in the other.
Dual filing obligations
Most cross-border businesses must file corporate returns in both the US and Canada, often with interrelated figures that must reconcile across both returns.
Permanent establishment risk
Sending employees to work across the border, opening an office, or maintaining inventory in a foreign country can inadvertently create a taxable presence — with retroactive consequences.
Withholding taxes on cross-border payments
Intercompany dividends, royalties, interest, and management fees are subject to withholding taxes unless reduced by treaty. Failure to withhold correctly creates liability for both payer and recipient.
Transfer pricing exposure
The IRS and CRA both scrutinize related-party transactions. Without proper documentation, either authority can reallocate income — potentially triggering double taxation.
Currency and timing differences
Tax calculations in both USD and CAD, combined with different fiscal year options, create reconciliation complexity that requires specialized expertise.
US vs Canada Corporate Tax: Key Differences
Understanding US Canada business tax differences is the foundation of effective cross-border planning. Here are the critical distinctions:
USUnited States
- Federal corporate rate: 21%
- State corporate tax: 0%–12% (varies by state)
- Pass-through entities (LLC, S-Corp) taxed at owner level
- Global minimum tax (GILTI) on foreign subsidiaries
- 30% withholding on most US-source income to non-US persons
CACanada
- Federal corporate rate: 15% (9% for Canadian-controlled private corps)
- Provincial corporate tax: 8%–16% (varies by province)
- No pass-through taxation — all corporations taxed at entity level
- Inter-corporate dividends generally tax-free between related corporations
- 25% withholding on dividends to non-residents (reduced by treaty)
Structuring Your Business Internationally
Cross-border tax planning starts with structure. The entity type and ownership arrangement you choose determines your tax exposure for years to come. Poor choices made at formation are expensive to unwind.
Parent-Subsidiary Structure
A common approach: a holding company in one country owns subsidiaries in the other. This provides liability separation, allows inter-company payments (subject to transfer pricing rules), and can facilitate tax-efficient repatriation of profits using treaty dividend rates. The optimal holding jurisdiction depends on your ownership structure and ultimate use of funds.
Branch Operations
A branch is not a separate legal entity — it is an extension of the parent company in the foreign country. Branches are simpler to establish but can expose the parent to direct liability and are subject to branch profit taxes in some jurisdictions. They also create permanent establishment by definition.
US LLC with Canadian Owner
This is one of the most common — and most misunderstood — structures. The US treats a single-member LLC as a disregarded entity; Canada treats it as a corporation. This "hybrid mismatch" can result in the same income being taxed twice without careful planning. We have extensive experience navigating this specific structure.
Beyond entity-level tax, the owners themselves may have personal cross-border obligations: US persons living in Canada have ongoing US tax filing for US citizens living in Canada duties, while Canadian-resident owners with US income may need US tax for Canadian residents guidance.
Not Sure Which Structure is Right for You?
Submit an inquiry and we'll determine whether we can assist with your cross-border structure and compliance questions.
Avoiding Double Taxation for Cross-Border Businesses
Double taxation — paying full corporate tax on the same income in both countries — is the greatest risk for businesses with US-Canada operations. The US-Canada Tax Treaty and domestic provisions provide several mechanisms to prevent it:
Permanent Establishment Rules
The treaty defines when a business in one country becomes taxable in the other. Without a PE, profits are generally only taxable in the home country.
Reduced Withholding Rates
Treaty reduces withholding on dividends (5%/15%), interest (0%), and royalties (0%/10%) — significantly lower than the standard 25-30%.
Foreign Tax Credit
Taxes paid in one jurisdiction can be credited against tax owed in the other, preventing the same profit from bearing full tax twice.
Transfer Pricing Arm's Length
Compliant intercompany pricing allows profit allocation between jurisdictions in a way both tax authorities accept, preventing reassessment-driven double tax.
Compliance Requirements: IRS & CRA Basics
Cross-border businesses face overlapping compliance requirements from both the IRS and CRA. Missing a filing — even an informational one — can trigger substantial penalties.
IRS Requirements (US)
- Form 1120 / 1120-F — US corporate return
- Form 5471 — Controlled foreign corporation reporting
- Form 8865 — Foreign partnership reporting
- Form 1042 — Withholding on US-source payments
- FBAR — Foreign accounts over $10,000
- Transfer pricing documentation (Section 482)
CRA Requirements (Canada)
- T2 — Canadian corporate income tax return
- T106 — Intercompany transactions (related parties)
- T1134 — Foreign affiliate reporting
- NR4 — Withholding on payments to non-residents
- HST/GST registration and reporting
- Transfer pricing documentation (Section 247)
How We Help Optimize Taxes for Cross-Border Businesses
As specialized international tax advisors for US-Canada operations, we bring a different level of expertise than a general accounting firm. We understand both tax systems simultaneously — not as two separate practices, but as an integrated cross-border framework.
Our approach begins with a comprehensive structural review: entity types, ownership chains, intercompany flows, treaty positions, and compliance gaps. From there, we develop a coordinated strategy covering both jurisdictions — designed to minimize your combined tax burden while keeping you fully compliant with both the IRS and CRA.
Whether you are a Canadian company expanding into the US market, a US business with Canadian subsidiaries, or an entrepreneur building a cross-border holding structure, our team provides the precise, experienced advisory you need to scale internationally with confidence.
For deeper background, explore our US–Canada cross-border tax guides.
Our Cross-Border Business Tax Services
Cross-Border Tax Planning
Strategic planning to minimize combined US and Canadian tax liability. We analyze your structure, income flows, and treaty positions to optimize your overall tax burden legally.
Corporate Tax Structuring
Design and implementation of tax-efficient entity structures for businesses operating across the US-Canada border — including holding companies, subsidiaries, branches, and partnerships.
Ongoing Tax Compliance
Coordinated preparation and filing of US and Canadian corporate tax returns, FBAR, transfer pricing documentation, and all required international information reporting.
International Expansion Advisory
End-to-end tax advisory for businesses entering a new market — from entity selection and registration to compliance setup, withholding analysis, and treaty optimization.
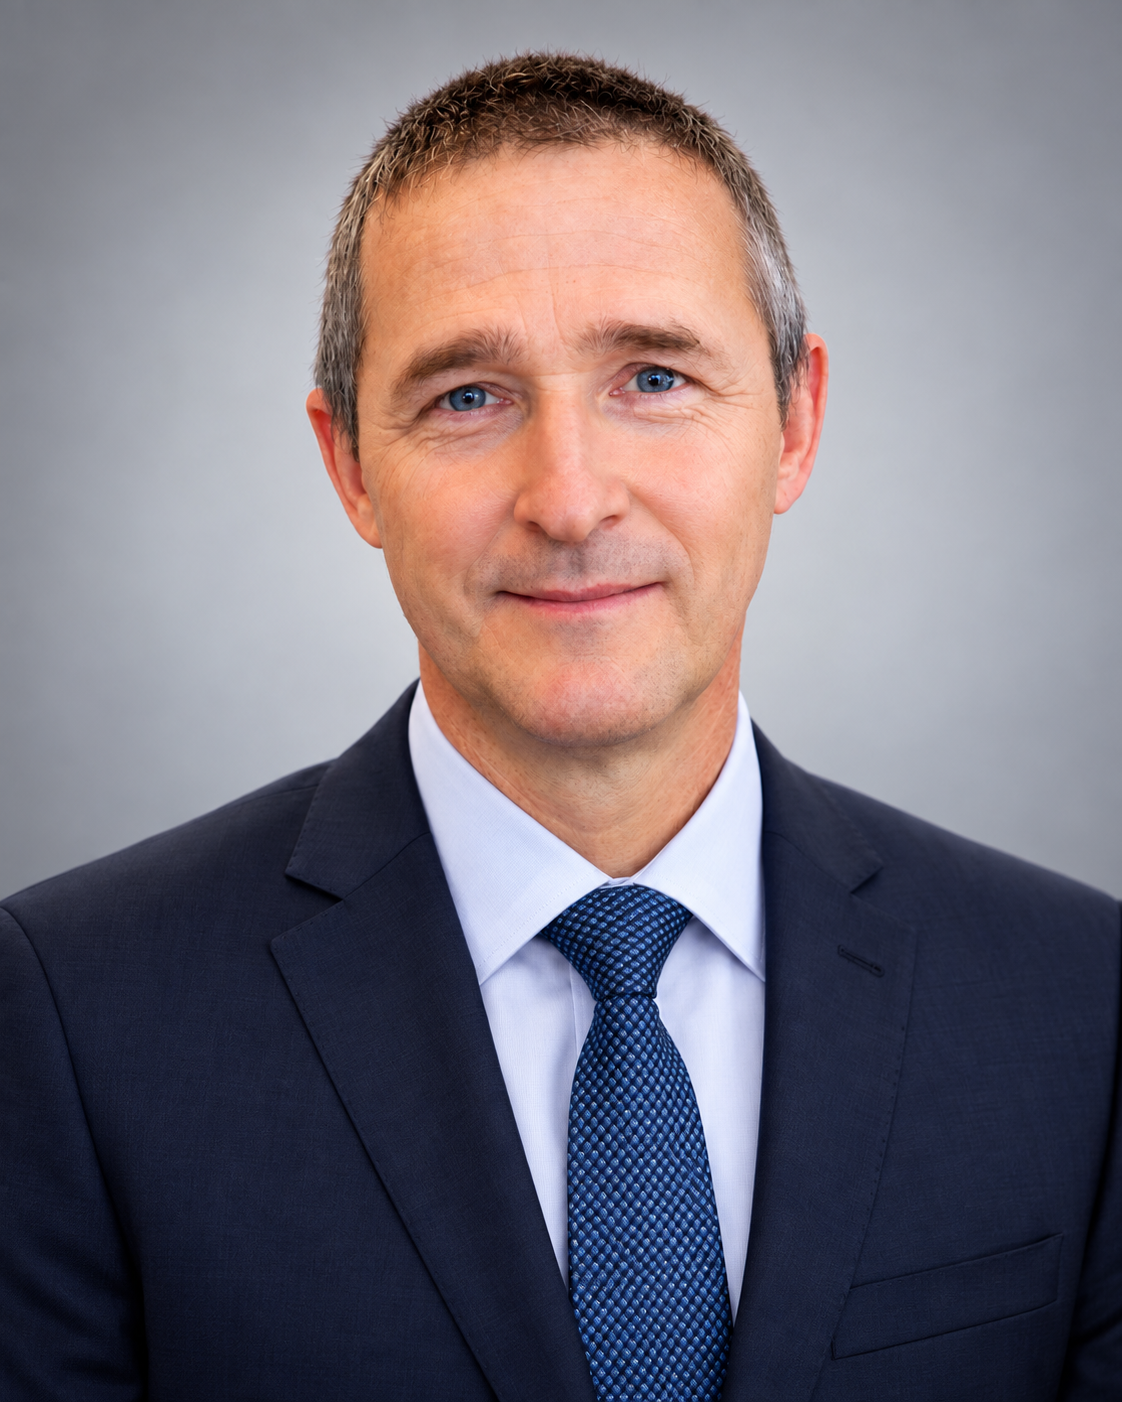
Principal, US CAN Tax Group · 25+ years of U.S. tax and cross-border experience
View Aleksandr's credentials →Cross-Border Tax Should Support Your Growth — Not Slow It Down
You don't have to diagnose your own structure, filings, or treaty positions. Submit an inquiry and we'll review whether we can assist and contact you about the appropriate next steps.
Frequently Asked Questions
Ready to Start Your Cross-Border Inquiry?
Submit an inquiry and a cross-border business tax specialist will contact you about the appropriate next steps.
We use optional analytics cookies to understand how visitors use our website and improve its performance. You can accept or reject analytics cookies.